November 18, 2026 cash-session edition. Fund quotes are delayed latest trades from 09:29–09:30 CST, reviewed at 09:45 CST, compared with November 17 closes. They are not live 09:45 quotations, cash-index closes or a consolidated advance/decline count. Fed October meeting minutes were scheduled for 13:00 CST and unreleased at this cutoff.
MARKET | SMALL-CAP BID, MIXED BREADTH
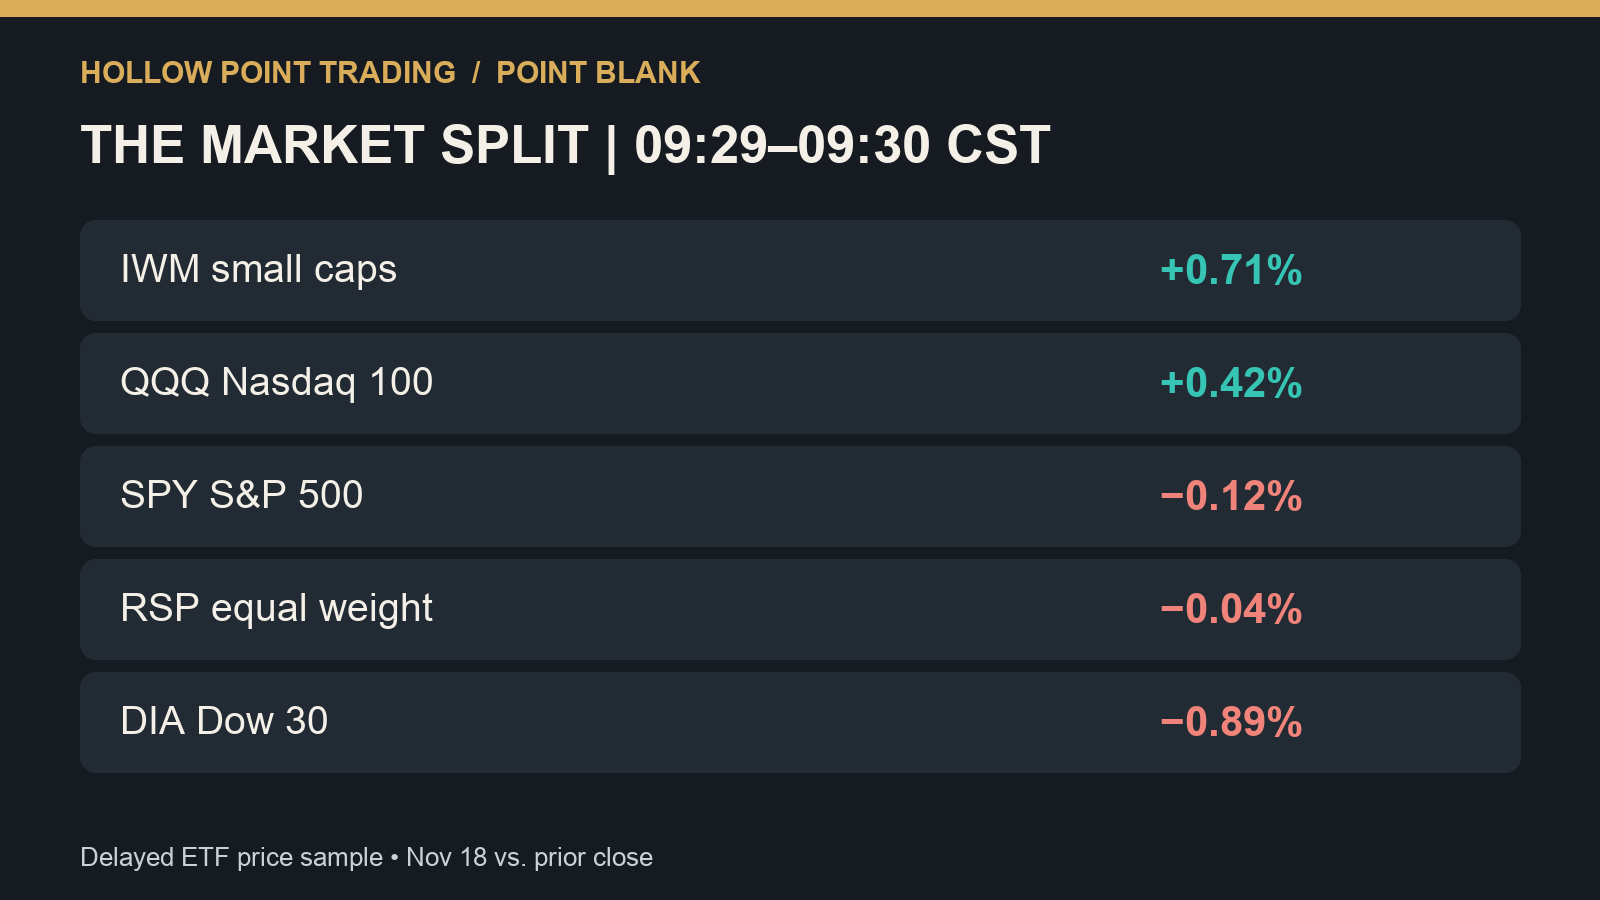
IWM was $270.96 (+0.71%) and QQQ $659.71 (+0.42%). SPY was $731.59 (−0.12%), DIA $502.81 (−0.89%) and equal-weight RSP $215.68 (−0.04%). Small caps and Nasdaq were positive while the Dow and equal weight did not confirm. IWM remained positive between sampled windows, but its path was not monotonic. RSP crossed both sides of its prior close. That is a weak breadth check, not proof that every small stock is stronger.
SECTORS | TECHNOLOGY UP; FINANCIALS AND ENERGY DOWN
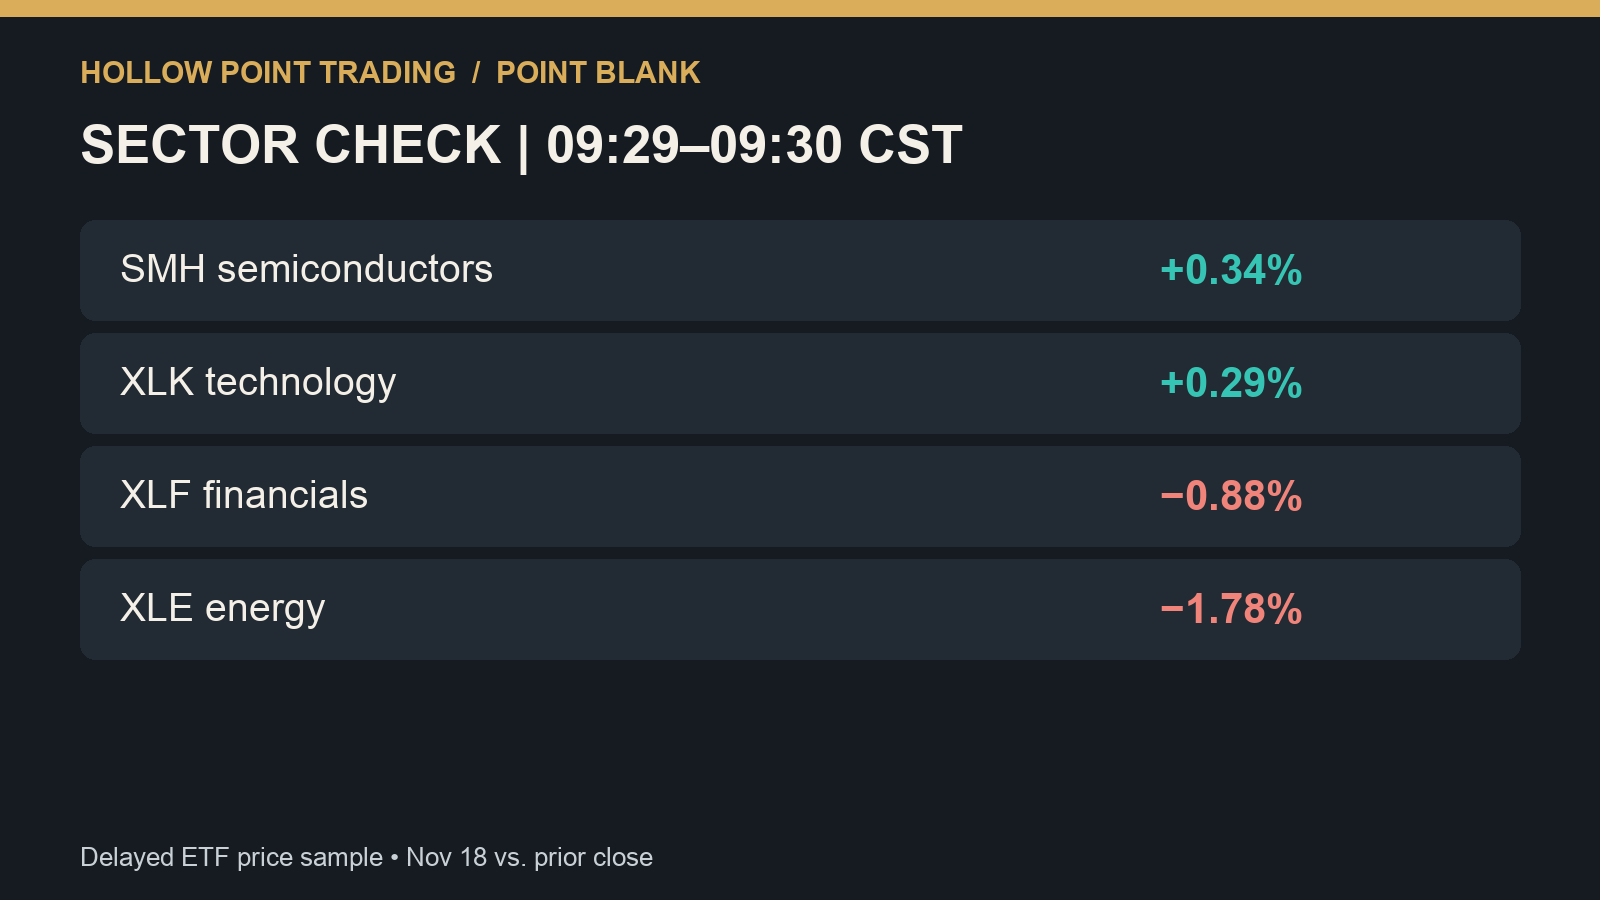
SMH was $461.65 (+0.34%) and XLK $163.74 (+0.29%) in the same delayed sample. XLF was $56.565 (−0.88%) and XLE $62.23 (−1.78%). A broad cyclical bid would have stronger support if financials and equal weight joined small caps. These ETF price comparisons are not claims about constituent earnings or causal drivers.
FUNDAMENTAL | A STRONG COMPANY REPORT IS ONE INPUT
Nvidia reported fiscal-third-quarter revenue of $115.8 billion on November 17, including $107.6 billion in Data Center. This is a concrete company-level AI infrastructure data point; it does not measure today’s breadth or explain each sector move. Compare reported demand with peers’ orders, margins and cash conversion before extending the conclusion across the market.
MACRO | THE HOUSING PIPELINE IS UNEVEN
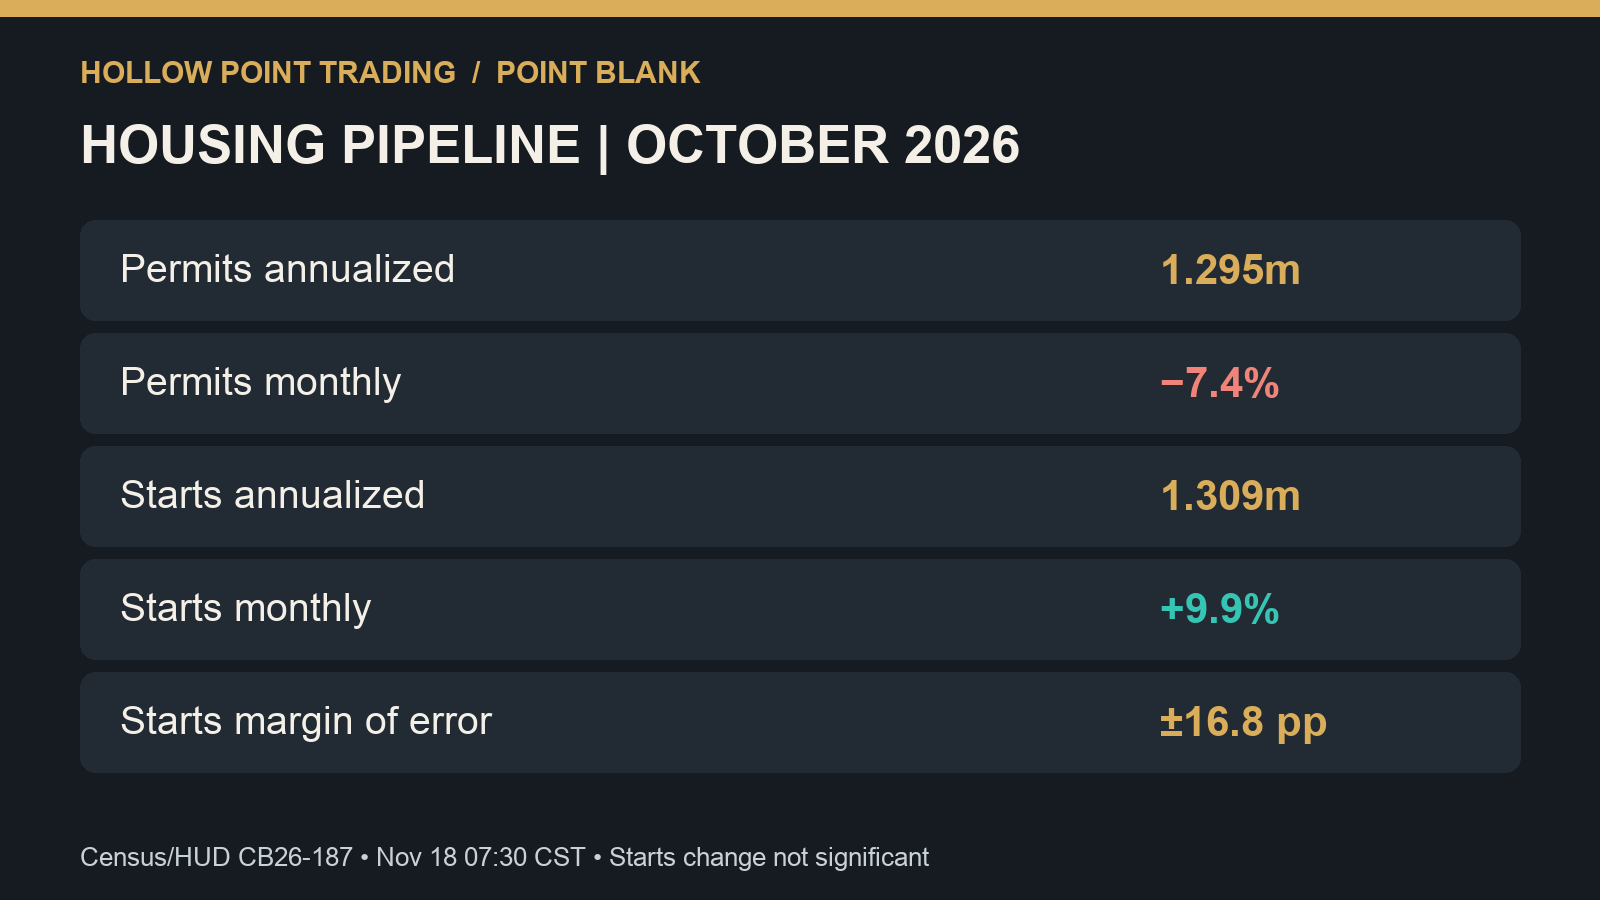
Census/HUD’s 07:30 CST October New Residential Construction release reported permits at 1.295 million annualized, down 7.4% from revised September. Starts were 1.309 million, up a printed 9.9% with a ±16.8% margin of error at the agency’s 90% confidence standard; the monthly starts change is not statistically distinguishable from zero. Permits and starts describe different stages. Housing-sensitive groups need orders, backlog and financing evidence of their own. The scheduled 13:00 CST Fed minutes may change the rate backdrop; this edition does not infer their contents.
CROSS-ASSET CHECK | MATCH THE CLOCKS
Energy weakness is compatible with pressure in oil, but an asynchronous commodity quote and the ETF snapshot cannot establish why every energy share moved. Treasury yields, continuous futures and ETF trades have different clocks and conventions. Treat them as separate observations unless timestamps and instruments line up. The accompanying visuals are explanatory data panels, not native TradingView technical captures.
DECISION ROUTE | TWO STEPS ON EACH SIDE
My near-term lean is selectively constructive for IWM and QQQ, neutral for the broader board while DIA, RSP, XLF and XLE lag. A bullish route needs a break and close above an observed opening swing, then a separate held retest, preferably with equal weight and financials improving. Losing that retest is local invalidation; wider invalidation is sustained loss of the prior full cash-session range on its own timeframe. The bearish route needs a break and close below observed support followed by a failed reclaim. One ETF percentage establishes neither route.
The six-level technical map is incomplete: authenticated Tanuki put/call-wall definitions and expiry scope, plus two upside and two downside checkpoints, were not verified for this edition. No option wall or gamma flip is inferred from ETF prices. No position, fill or result is asserted.
Which would change your read first: equal weight and financials joining the small-cap bid, or IWM losing its positive print while the Dow stays weak?
Sources and cutoffs: delayed fund-price quotes, latest trades 09:29–09:30 CST Nov 18, reviewed 09:45 CST; U.S. Census Bureau/HUD, October New Residential Construction CB26-187, released 07:30 CST Nov 18; Nvidia fiscal-third-quarter investor release Nov 17; Federal Reserve November 2026 meeting calendar.